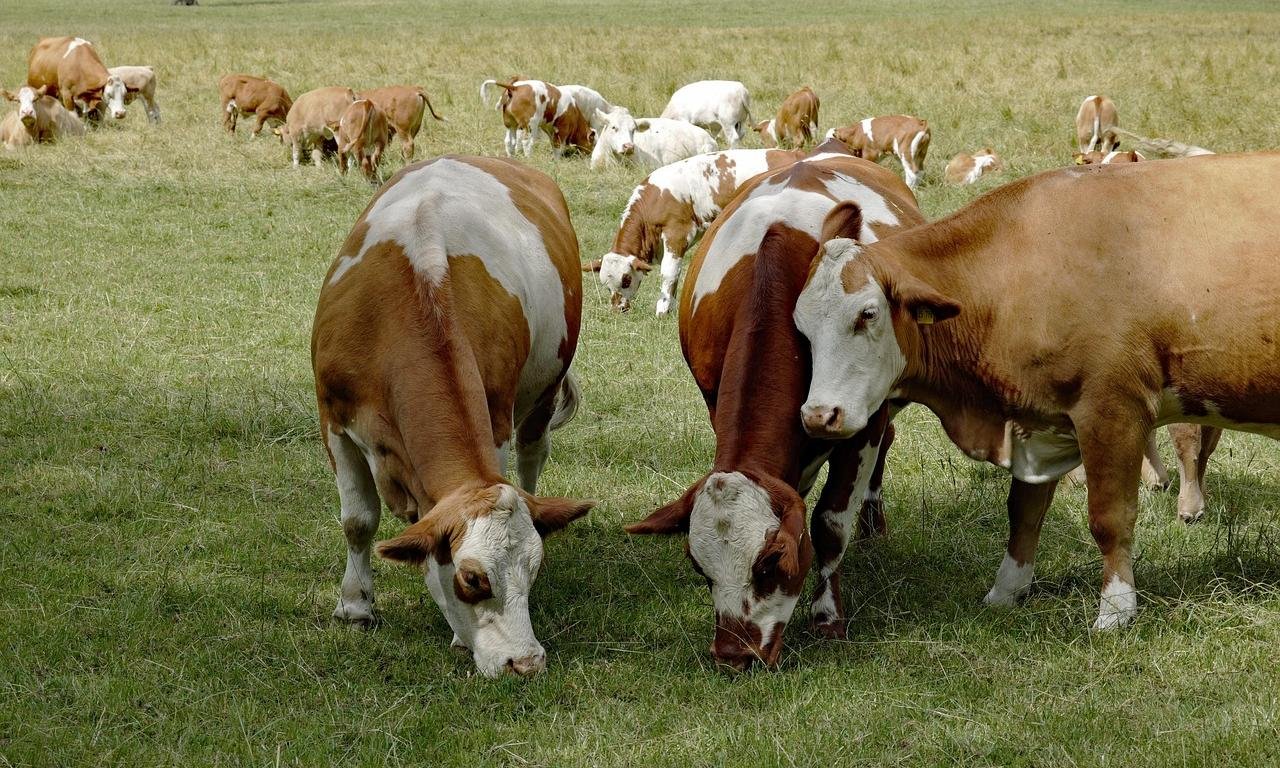
Great Britain’s milk production declined by 4.1% year-on-year in October 2026, reflecting challenging farm economics, rising input costs and the impact of adverse weather conditions. However, milk deliveries remained above the five-year average, highlighting the continued resilience of the country’s dairy supply despite growing pressures on producers.
According to the October 2026 dairy market review published by the Agriculture and Horticulture Development Board (AHDB), daily milk deliveries averaged 33.99 million litres during the month, bringing total estimated production to 1,053 million litres. Although this represented a decline compared with October 2025, it was still the second-highest October supply recorded in the past decade.
Milk deliveries between April and October 2026 were 2.6% lower than during the corresponding period in 2025. The decline partly reflects comparisons with exceptionally strong production levels recorded during the previous autumn.
Farm Economics and Disease Pressures Affect Milk Production
Several factors contributed to the reduction in British milk production. Although farmgate milk prices increased between August and October as processors competed to secure supplies affected by heat and drought, dairy farmers continued to experience pressure on production margins.
Higher costs associated with forage, fuel and fertiliser limited the benefits of improved milk prices. The Milk to Feed Price Ratio also weakened, indicating that higher milk revenues were insufficient to compensate fully for increasing input expenditure.
Bluetongue virus emerged as another concern for the dairy sector, spreading rapidly across parts of Great Britain. While most dairy herds reportedly opted for vaccination, disease-related uncertainties added pressure to milk production.
Feed costs also experienced upward movements associated with global drought conditions and the war in Ukraine. Meanwhile, geopolitical tensions in the Middle East contributed to elevated energy and agricultural input costs.
Regional differences were also evident. Milk pools in the South West experienced greater supply constraints, while producers further north were reportedly less affected by drought and bluetongue-related challenges.
Milk Prices Show Mixed Movements Across Contracts
Farmgate milk prices recorded positive movements through much of the summer and autumn. According to Defra, the latest published farmgate milk price for September 2026 stood at 38.45 pence per litre (ppl), representing an increase of 1.78ppl compared with August.
However, November price announcements were largely steady, with some processors introducing increases and others maintaining existing rates.
Among retail-aligned liquid milk contracts, Müller Tesco reduced its price by 0.21ppl, while Müller Co-op Dairy Group and Sainsbury’s increased prices by 0.72ppl and 0.14ppl, respectively. Müller M&S and Waitrose maintained their prices.
Non-aligned liquid contracts generally remained steady to firm. Crediton Dairy announced an increase of 2.00ppl, while Müller Direct raised its price by 0.50ppl and Pembrokeshire Creamery introduced a 1.13ppl increase.
In the cheese sector, Lactalis announced its sixth consecutive monthly price increase, raising its milk price by 0.57ppl. Meanwhile, UK Arla Farmers Manufacturing reduced its price by 0.45ppl following seven consecutive months of increases.
Global Milk Production Continues to Expand
While British milk deliveries declined, global milk production continued to increase across several major dairy-producing regions.
According to the review, milk deliveries across selected global regions averaged 821.8 million litres per day in August, representing a year-on-year increase of 13.4 million litres, or 1.7%.
The United States recorded particularly strong growth, with milk production increasing 2.4% to 284.8 million litres per day. Expansion of the dairy herd, favourable farm margins and lower culling rates supported production growth.
European Union milk deliveries increased by 0.6% to an estimated 393.3 million litres per day. Meanwhile, New Zealand recorded a 2.4% increase to 46.3 million litres per day, supported by favourable weather and firm milk prices.
Australia’s production rose 4.2% to 22.2 million litres per day, while Argentina recorded a 2.2% increase.
However, Rabobank expects global milk supply growth to slow to approximately 0.5% during the second half of 2026, with production expected to stabilise in 2027.
Wholesale Dairy Markets Experience Pressure
Despite tightening supplies of cheese and butter during the second quarter, wholesale dairy markets experienced downward price movements in August.
Butter stocks declined by 7.6%, although inventories remained relatively high. Cheese stocks decreased by 3.3%, supported by lower production and stronger export activity, despite increasing imports.
The August wholesale market recorded the following movements:
| Dairy product | August price (£/tonne) | Monthly change |
|---|---|---|
| Cream | £1,528 | -£180 |
| Butter | £3,300 | -£240 |
| Mild cheddar | £3,290 | -£40 |
| Skimmed milk powder | £2,930 | +£200 |
Weakening demand and easing concerns about milk availability contributed to declining cream prices. Butter markets remained under pressure from elevated stock levels, while weakness in dairy fats affected cheddar prices.
In contrast, skimmed milk powder recorded a stronger performance, gaining £200 per tonne during the month.
The latest Global Dairy Trade auction offered a mixed picture, with the overall index increasing 3.0% to US$4,166 per tonne. Whole milk powder prices rose 5.9%, skimmed milk powder increased 3.1% and cheddar gained 8.6%. However, butter declined 4.7%, while anhydrous milk fat fell 3.2%.
Consumer Demand Shifts Across Dairy Categories
Retail purchasing trends in the 12 weeks ending 3 October 2026 showed a 0.6% increase in overall cow’s dairy volumes, while consumer spending rose 1.4%.
Growth was driven primarily by cheese, yoghurt, yoghurt drinks and cream, which offset declining milk consumption.
Milk volumes decreased 0.4% year-on-year, although spending increased 1.1% due to higher average prices. Whole milk volumes grew 3.1%, while semi-skimmed and skimmed milk declined by 2.2% and 2.8%, respectively.
Cheese volumes increased 1.8%, with growth particularly strong in other cow’s cheese, snacking cheese and speciality and continental varieties. However, cheddar volumes declined 1.7%.
Yoghurt and yoghurt drink volumes recorded stronger growth of 7.2%, supported by increased demand for plain, healthy and fat-free yoghurt products.
Butter volumes declined 2.5%, while consumer spending fell 6.9%, reflecting lower average prices. Cream volumes increased slightly by 0.3%.
Outlook for the Great Britain Dairy Industry
The October production figures indicate that Britain’s dairy sector continues to face a complicated supply and pricing environment. Although milk deliveries remain above the five-year average, declining production, rising input costs and animal health challenges are creating uncertainty for dairy farmers.
At the same time, strong global milk production, elevated dairy inventories and mixed wholesale prices are limiting processors’ ability to sustain higher farmgate prices.
The coming months will therefore depend on the balance between milk availability, international commodity demand and production economics. Processors may need to offer competitive milk prices to maintain supplies, particularly as farm margins remain under pressure.