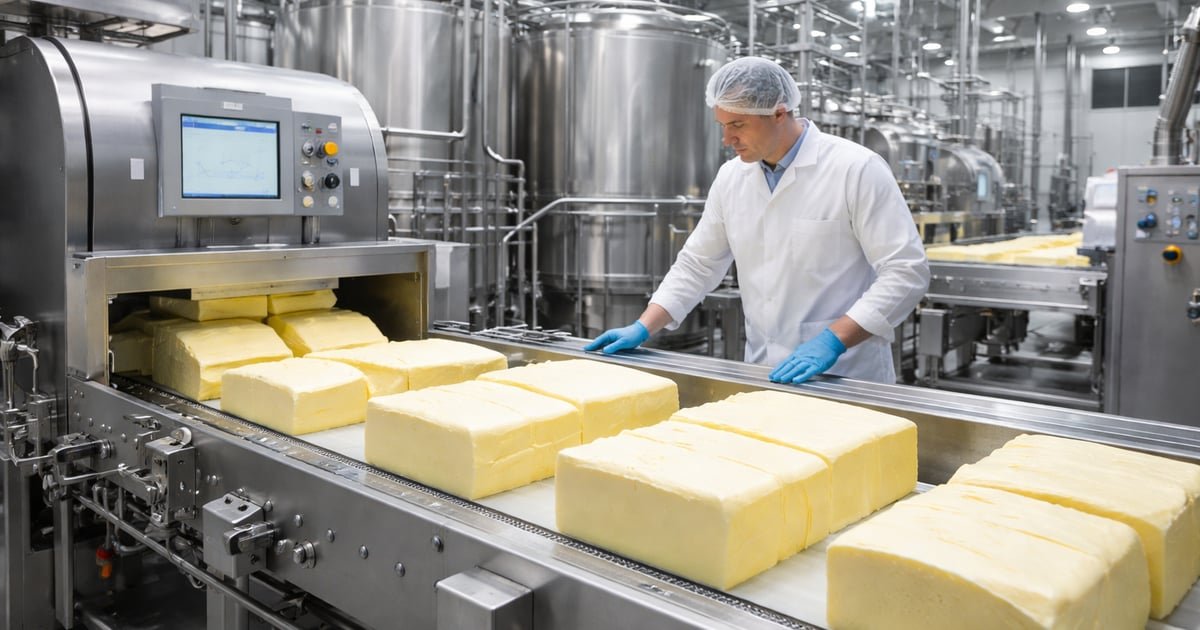
Declining milk deliveries and rising feed costs are supporting European butter prices, although subdued demand and available stocks continue to limit the potential for a strong market recovery.
European butter prices are showing signs of stabilisation in October 2026 as seasonal declines in milk production and higher dairy farming costs begin to tighten fat availability. However, demand remains cautious, preventing a sharp price rebound across the European dairy market.
According to Commodity Board, fresh butter prices in Poland have increased modestly, while European reference prices and futures indicate a cautiously firmer outlook towards the end of 2026. Market participants are weighing the impact of lower milk supplies against weak consumer purchasing power and lingering uncertainty over dairy product demand.
The market’s direction will largely depend on whether declining milk production becomes significant enough to outweigh the continued restraint in retail and foodservice demand.
Butter prices show modest recovery
Fresh butter containing 82% fat, originating from Grudziądz, Poland, was quoted at €3.60 per kilogram on a free-carrier (FCA) basis on 13 October 2026. This represented an increase from €3.52 per kilogram in late September, indicating a gradual improvement in physical market prices.
The report placed average European Union butter reference prices at approximately €4,145 per tonne, around 0.5% higher week on week. Despite the recent increase, prices remained almost 30% below their levels a year earlier, highlighting the scale of the market correction since the highs recorded in 2025.
European Energy Exchange (EEX) butter futures for late 2026 were trading broadly between €4,000 and €4,200 per tonne, suggesting that traders were anticipating moderate rather than dramatic price increases.
The difference between prices for individual origins and EU-wide reference indicators also highlights the importance of product specifications, delivery terms and market location when comparing butter quotations.
Declining milk deliveries tighten cream availability
Seasonal declines in milk production are emerging as an important factor supporting butter values. Milk intake at German dairies has begun to fall as the industry approaches its usual late-autumn production trough.
The report stated that German milk intake in week 40 was 0.2% lower than the previous week, while year-on-year growth had narrowed to 0.6%. In France, milk collections were reported to be 2.4% below the corresponding period a year earlier, reducing the availability of cream used in butter manufacturing.
Rabobank expects EU raw milk production to decline by approximately 2% in the fourth quarter of 2026 compared with the same period in 2025. The outlook reflects pressure from adverse summer weather, reduced forage availability and rising costs on dairy farms.
Lower milk intake can reduce the supply of cream available to processors, potentially increasing competition for milk fat. However, the effect on butter prices will depend on demand, inventories and how processors allocate milk between butter, cheese, milk powders and other dairy products.
Feed costs put pressure on dairy farm margins
Higher feed expenses are adding to the challenges faced by European milk producers. Drought and summer heat in some regions damaged pastures and reduced forage yields, leaving farmers more dependent on purchased feed for the winter period.
Elevated energy and fertiliser costs are adding further pressure to production budgets. Although average EU farmgate milk prices reportedly increased to 43.11 eurocents per kilogram in September 2026, they remained approximately 19% below September 2025 levels.
This combination of lower milk prices compared with the previous year and higher production costs is squeezing farm profitability. Some farmers may respond by adjusting feed rations, prioritising their most productive animals or reducing herd sizes. Such decisions could affect milk yields and contribute to tighter supplies in the coming months.
For dairy processors, sustained pressure on farm margins could eventually influence milk availability and procurement costs, with consequences for butter and other dairy commodity prices.
Demand continues to limit price gains
Despite the supply-side support, European butter markets face demand-related challenges. Pressure on household purchasing power from broader food and housing costs has encouraged consumers to control spending, weighing on some premium dairy products.
Butter has also underperformed certain dairy protein products, including skimmed milk powder, according to the market analysis. This relative weakness has left milk fat comparatively inexpensive within the wider dairy commodity market, potentially supporting its use in retail and foodservice.
Nevertheless, available stocks and competition among suppliers could limit further price increases. Processors must balance higher input costs against what retailers, food manufacturers and consumers are willing to pay.
Cautious outlook for the coming months
The outlook for European butter remains moderately firm, provided milk supplies continue to tighten and demand does not deteriorate substantially. Buyers may consider covering immediate requirements while remaining cautious about committing to larger volumes further into 2027. Sellers, meanwhile, face opportunities to protect margins but must account for competition and uncertain consumption.
Weather conditions, winter feed availability, milk yields and retailer pricing strategies will remain important variables. A more severe deterioration in forage availability could strengthen supply-side pressure, while weaker economic conditions or aggressive retail discounting could limit or reverse recent gains.
For Europe’s dairy industry, the current market illustrates the close relationship between farm-level production costs, seasonal milk availability and commodity pricing. Whether the recent recovery continues will depend on how these competing supply and demand forces develop through winter.